What is Indexed Universal Life?
Provide death benefit protection AND a means to create a tax free retirement income.
We do this by funding a life insurance contract and allow compounding interest to grow funds over time and then fund a tax-free retirement income.
An IUL provides protection from premature loss
We are taking advantage of section 7702 of the IRS code
- In the event of death, death benefit is 100% tax-free(This provides for loss of income protections)
- Solid death benefit with growing cash value(How strong depends on your choices)
- 100% creditor-proof(When paid in monthly installments to beneficiaries, creditors cannot make claims on this money)
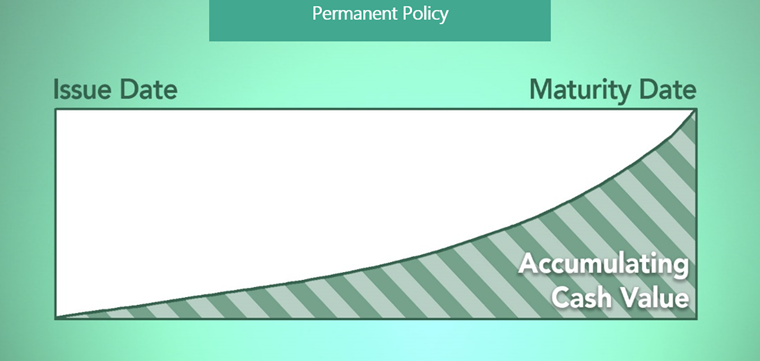
A Permanent Policy
From the issue date to the maturity date, the policy stays in force and the cash value keeps accumulating — growing faster in the later years as compounding takes hold.
Universal Life Policy
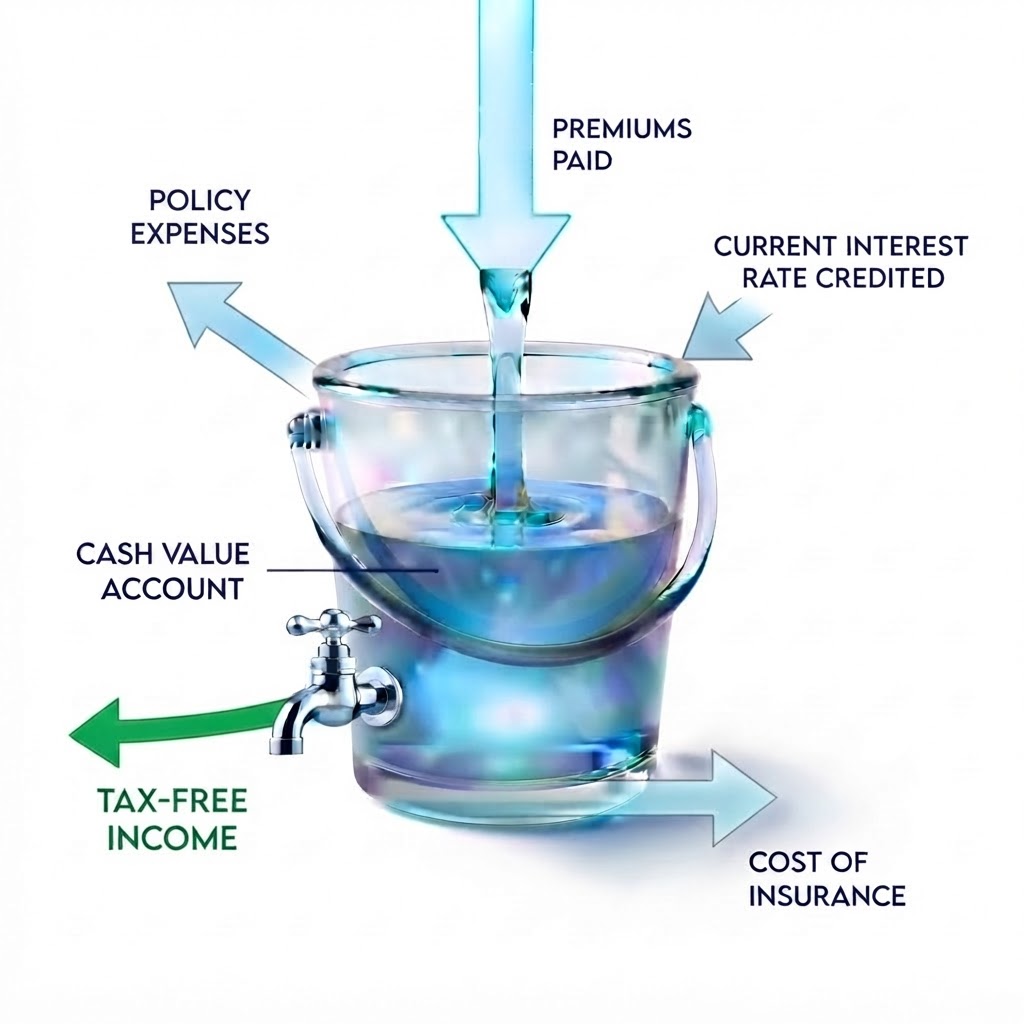
How the moving parts of a universal life policy fit together:
- Premiums paidYour contributions flow into the policy
- Policy expensesA portion of each premium covers policy charges
- Cash Value AccountThe remainder accumulates in your cash value account
- Current rate from the companyInterest is credited to the cash value account
- Cost of insuranceDeducted monthly from the cash value account
IUL Is protected from risk of loss
- Never lose moneyCurrent interest rate is credited each year
- Average annual return over last 20 years is 8.37%0% floor – no loss of gains · Gains are capped with participation rates
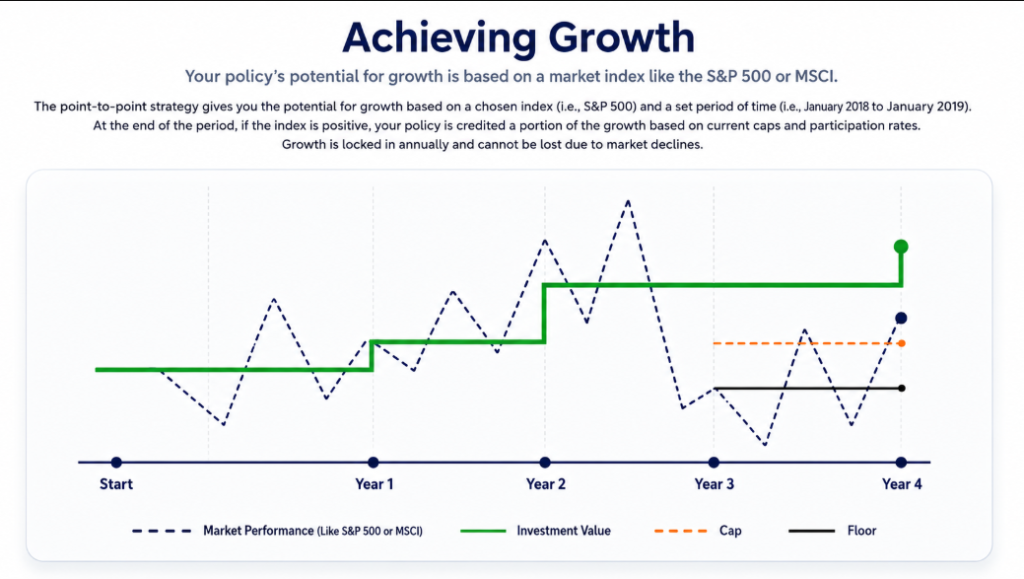
- Annual lock and resetAnnual gains are captured and never decrease
An IUL is Indirectly linked to an Index, such as the S&P 500.
Your policy’s potential for growth is based on a market index like the S&P 500 or MSCI.
The point-to-point strategy gives you the potential for growth based on a chosen index and a set period of time. At the end of the period, if the index is positive, your policy is credited a portion of the growth based on current caps and participation rates. Growth is locked in annually and cannot be lost due to market declines.
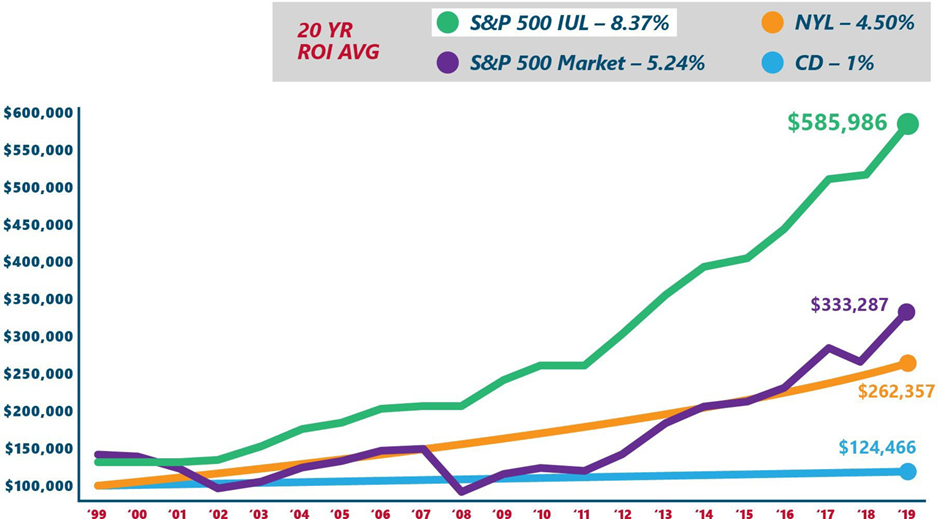
20-Year Comparison of Results
20 year average return on investment, and value at the end of the period:
| Vehicle | 20 Yr ROI Avg | Value |
|---|---|---|
| S&P 500 IUL | 8.37% | $585,986 |
| S&P 500 Market | 5.24% | $333,287 |
| NYL | 4.50% | $262,357 |
| CD | 1.00% | $124,466 |
Funding Your policy
- Small, steady and consistent contributions$3 per day = $90 per month accumulates and compounds over time.
- Lump Sum Distribution, spread over first few years of policy$2,000 – $10,000 annual contributions for 3 – 7 years
- In both methods, the IUL account value grows due to compound interest
IUL Distributions can be set up to last a lifetime
- An IUL has built-in safeguards and guarantees to ensure the income continues for a lifetime
- The beneficiary will ALWAYS get more money out of the IUL than they ever put in
Do you want to just leave money for your grandkids, OR do you want to change their lives forever and leave a legacy that lasts generations?
An IUL uses Participating Policy Loans for tax-free lifetime income in retirement years
- Taxes are most likely going to go up in the future (due to the national debt)
- Supplement retirement income with tax-free participating policy loans
- Give yourself a loan from the death benefit into your wallet
- The IUL is essentially converted to income with participating loans, which means NO TAXES ARE DUE WHEN INCOME is received